
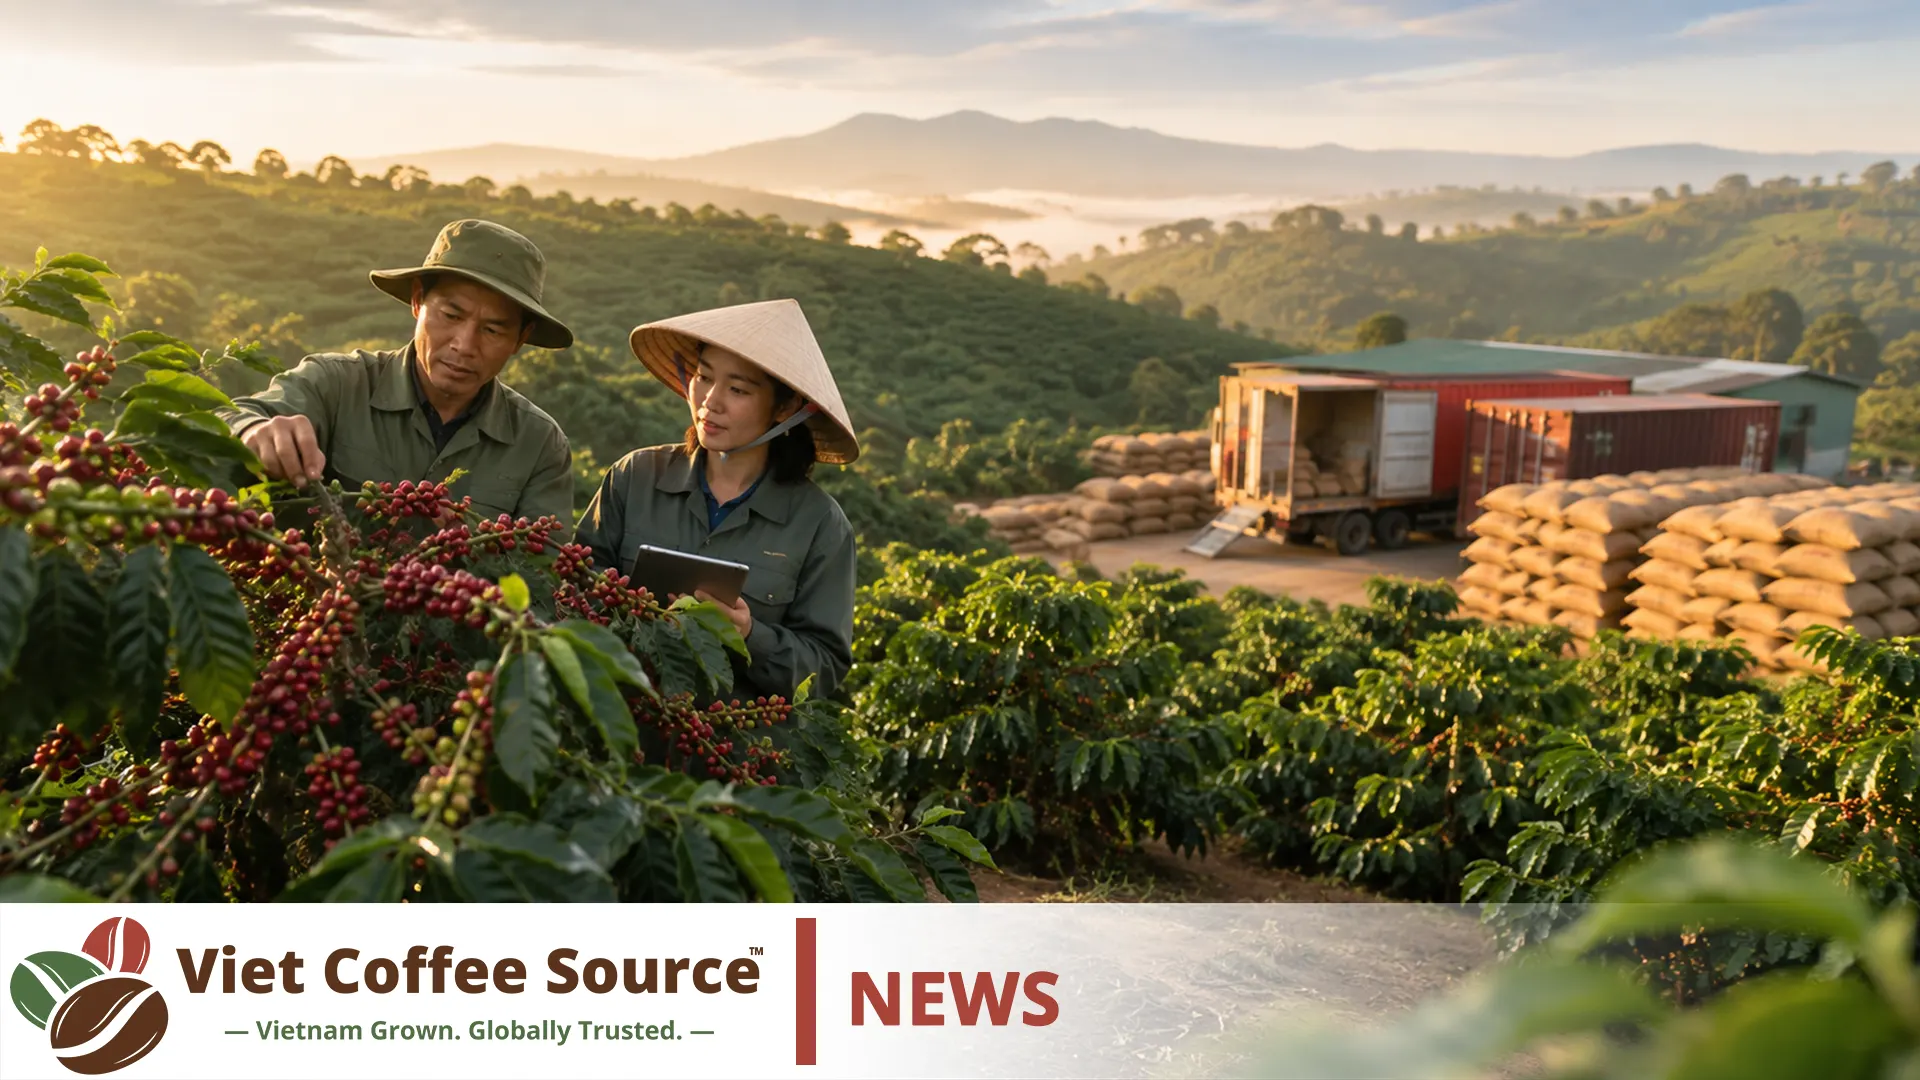
Robusta Market Watches Vietnam Crop Prospects and Export Availability
The international Robusta market is closely watching Vietnam’s crop prospects and export availability as buyers assess whether improving production forecasts will translate into a steady flow of physical coffee. Vietnam remains the world’s most important Robusta origin, making developments in its farms, domestic inventories and shipment programme influential across futures markets, espresso supply chains and soluble coffee manufacturing.
Expectations for a larger Vietnamese crop have supported a more positive global supply outlook. However, production forecasts alone do not determine how much coffee will be available to international buyers. Farmer selling decisions, existing contracts, domestic processing demand, warehouse stocks and logistics capacity all affect the volume and timing of exportable supply.
Vietnam’s production outlook improves
In late May 2026, the United States Department of Agriculture revised its estimate for Vietnam’s 2025/26 coffee production upward to 31.7 million 60-kilogram bags. Production for the 2026/27 coffee year was forecast at approximately 32.5 million bags.
The upward revisions reflected stronger investment in farms following several years of elevated coffee prices. Producers have had greater incentives to improve fertilisation, irrigation, pest management and the renovation of ageing coffee trees, helping support yield recovery in important Central Highlands production areas.
A crop of this size would improve the potential availability of Vietnamese Robusta and provide the international market with a larger supply buffer. It could also ease some of the pressure experienced by roasters and manufacturers during periods when inventories were limited and replacement costs rose rapidly.
Nevertheless, the forecast remains exposed to weather conditions during key stages of flowering, cherry development and harvesting. The final crop may differ from early estimates if rainfall distribution, temperatures or irrigation availability move outside normal seasonal patterns.
Weather remains a major uncertainty
Weather risk continues to prevent the market from treating the improved outlook as guaranteed supply. Expectations surrounding a potentially strong El Niño event have raised concern about possible drought conditions in Southeast Asia, including Vietnam.
Reduced rainfall can affect soil moisture, flowering and cherry development, particularly on farms with limited irrigation access. Prolonged heat can also increase water requirements and place additional pressure on production costs.
Excessive rainfall can create a different set of problems. Heavy rain during harvesting and drying can delay farm operations, increase moisture risks and make it more difficult to maintain consistent green coffee quality.
Market participants are therefore monitoring conditions across Đắk Lắk, Lâm Đồng, Gia Lai, Đắk Nông and other production areas rather than relying only on national crop projections. Differences in rainfall, farm investment and tree condition can produce uneven results between individual Vietnamese coffee origins.
Export volumes increase as average prices decline
Vietnam exported approximately 1.1 million tonnes of coffee during the first six months of 2026, an increase of 9.7% compared with the same period a year earlier. Export revenue reached around USD 4.78 billion, declining by 14.4% as the average export price fell.
The average export price during the January–June period was approximately USD 4,435 per tonne, down 22% year-on-year. The combination of higher volume and lower revenue showed that more coffee was moving into international markets, but at less favourable average price levels than during the previous period of exceptionally high values.
For the Robusta market, stronger Vietnamese shipments provide evidence that physical availability is improving. They also increase competition among exporters and may give buyers more opportunities to compare differentials, shipment periods and product specifications.
However, cumulative national export figures do not show how much uncommitted coffee remains available for immediate purchase. Part of the reported volume may represent contracts agreed months earlier, while some new-crop coffee may already be allocated to regular customers or domestic processors.
Global Robusta shipments strengthen
International Coffee Organization data showed that global green Robusta exports reached 4.34 million bags in May 2026, increasing by 4.8% from 4.14 million bags in May 2025. Robusta was the only major coffee group to record year-on-year export growth during the month.
The increase contrasted with weaker shipments across the Arabica groups and raised Robusta’s share of global green coffee trade. This strengthened availability is important for buyers using Robusta in espresso blends, instant coffee, ready-to-drink products and large-scale commercial roasting.
Global Robusta exports over the twelve months ending in May 2026 reached 59.28 million bags, compared with 53.41 million bags in the previous corresponding period. Vietnam’s export performance was a major factor behind the more active Robusta trade flow.
Even with stronger shipments, the market remains sensitive to changes in Vietnam because alternative Robusta origins cannot always replace Vietnamese volumes immediately. Differences in crop calendars, processing methods, bean size, defect profiles and logistics can limit substitution between origins.
Robusta prices remain responsive to supply signals
The ICO’s average Robusta indicator increased by 1.7% in June 2026 to 169.39 US cents per pound, while London futures rose by 2.7% to an average of 155.90 US cents per pound. The movement occurred even as broader coffee supply expectations improved.
The price response showed that the Robusta market was balancing higher crop forecasts against weather concerns, geopolitical risks and the availability of certified exchange stocks. Positive production estimates can place downward pressure on prices, but unexpected disruptions may quickly reverse that direction.
London-certified Robusta stocks increased by 4.8% from May to June, closing the month at approximately 0.68 million bags. The rise provided some evidence of improving deliverable supply, although the stock level remained limited compared with the scale of global consumption and trade.
Certified stocks also represent only one part of physical availability. Coffee held by exporters, traders, domestic manufacturers and buyers outside exchange warehouses may not be visible in headline stock figures.
Farmer selling behaviour affects availability
Vietnamese farmers do not necessarily release coffee immediately when production rises. When producers have stronger financial positions or expect prices to recover, they may hold stocks and sell gradually rather than delivering the entire crop shortly after harvest.
This behaviour can create a difference between estimated crop size and the volume offered in the domestic market. Exporters may face difficulty securing replacement coffee even when national production appears sufficient on paper.
Lower prices may also reduce farmers’ willingness to sell unless they need cash for farm investment or household expenses. Conversely, a sudden futures rally or favourable exchange-rate movement can encourage more rapid selling and temporarily improve exporter access to physical supply.
Buyers should therefore monitor domestic trading conditions alongside international futures. Local differentials, farmer offers and exporter inventories can provide a clearer indication of near-term availability than production forecasts alone.
Domestic processing competes for part of the crop
Vietnam is expanding its production of roasted, soluble and value-added coffee products. This growth means that not every additional bag produced will automatically enter the international green coffee market.
Domestic factories require Robusta for instant coffee, three-in-one products, extracts and industrial blends. As processing capacity grows, manufacturers may secure more coffee through long-term purchasing arrangements or direct relationships with producing areas.
This competition can influence export availability for particular grades. Standard commercial Robusta may be widely available, while specific screen sizes, moisture levels, processing methods or defect tolerances remain more limited.
International buyers should define specifications early and avoid assuming that a larger national crop guarantees unrestricted availability of every grade. Sample approval, contract confirmation and production scheduling should be completed before the preferred shipment window becomes crowded.
Quality differences become more important in a larger crop
Higher production can increase the quantity offered by exporters, but it does not automatically ensure uniform quality. Coffee may come from farms with different harvesting practices, drying systems, storage conditions and levels of investment.
Buyers should verify screen size, moisture, foreign matter, black and broken beans, processing method and sensory suitability before confirming large volumes. Pre-shipment samples should represent the contracted lot rather than a general reference sample from the same region.
Exporters should connect lot identification and warehouse controls with structured quality and compliance procedures. Clear records reduce the risk of mixing coffee from different suppliers or delivering specifications that differ from the approved sample.
Traceability delivering specifications that differ from the approved sample.
Traceability is also becoming increasingly relevant for European buyers. Farm and plot information must remain connected to processing and export records, particularly when customers require deforestation-related due diligence or origin verification.
Logistics determine when supply reaches buyers
Export availability depends not only on coffee stocks but also on the ability to process, bag, inspect and transport the product. Congestion, equipment availability, container shortages or changes in shipping routes can delay delivery even when coffee is physically available in Vietnam.
Longer transit routes between Asia and Europe can increase freight, insurance and financing costs. These expenses may reduce the benefit buyers expect from lower green coffee prices and can influence decisions about shipment size or delivery timing.
Suppliers should confirm processing capacity, container bookings and export documentation before committing to narrow shipment periods. Buyers should also distinguish between an indicative offer and a fully confirmed allocation supported by available coffee and logistics capacity.
Buyers balance improved supply against remaining risks
The improved Vietnamese crop outlook provides a more favourable foundation for the Robusta market than the severe supply concerns seen in earlier periods. Higher exports and rising certified stocks suggest that availability is beginning to strengthen.
Nevertheless, the market remains vulnerable to weather changes, farmer stockholding, domestic processing demand and logistics disruption. Any significant revision to Vietnam’s crop estimate can affect futures prices and physical differentials because of the country’s dominant role in global Robusta supply.
Importers may manage this uncertainty by dividing purchases across several shipment periods, confirming specifications early and maintaining communication with suppliers about crop development and domestic availability. A staged purchasing strategy can reduce dependence on a single price level or delivery window.
The Robusta market will continue watching whether Vietnam’s projected production is converted into consistent exportable supply. Buyers that combine market monitoring with physical verification, clear contracts and reliable supplier relationships will be better positioned to respond as conditions change.
International buyers seeking Vietnamese Robusta with defined grades, shipment periods and documentation requirements can submit a wholesale inquiry based on their required specifications, volume, destination and delivery terms.